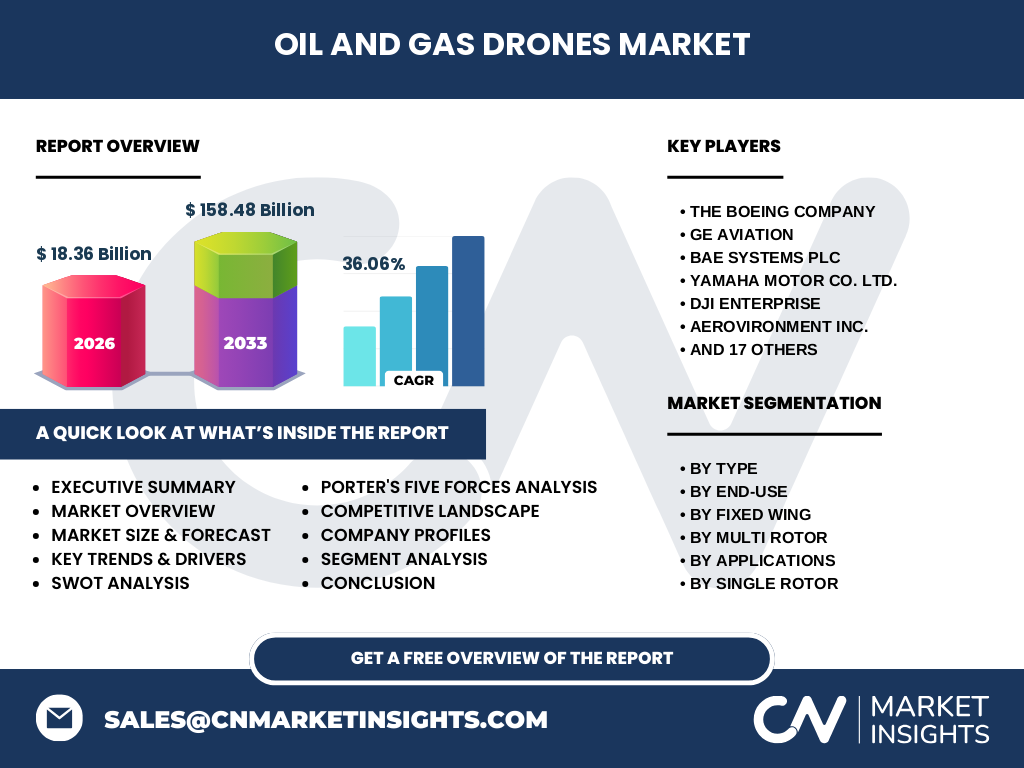
Market overview and structural scope of the Oil And Gas Drones Market
Our analysis indicates that the Oil And Gas Drones Market represents a transformative technological paradigm shift, valued at 18.36 Billion in 2026. This sector encompasses aerial robotic systems deployed across upstream, midstream, and downstream operations. Industry significance lies in mitigating catastrophic asset failures, reducing carbon footprints during flare stack monitoring, and complying with stringent environmental mandates set by bodies like the EPA and PHMSA.
Key market drivers, restraints, challenges, and opportunities shaping the Oil And Gas Drones Market industry trends
Structural growth is propelled by escalating demand for remote asset integrity management and autonomous pipeline surveillance. Conversely, stringent airspace integration policies enforced by the FAA pose notable operational restraints. Cybersecurity vulnerabilities remain a critical industry challenge. However, emerging opportunities in methane leak detection using advanced hyperspectral payloads offer high-margin expansion pathways for specialized operators.
Emerging trends and growth patterns in the Oil And Gas Drones Market
The sector is witnessing a decisive shift toward beyond visual line of sight (BVLOS) operations for vast transnational pipeline networks. Automated docking stations deployed in remote Permian Basin oilfields enable continuous, pilotless monitoring. Furthermore, the integration of edge computing and artificial intelligence allows real-time corrosion detection, drastically reducing downtime for offshore platforms in the North Sea.
COVID-19 impact analysis and recovery trajectory for Oil And Gas Drones Market
The pandemic initially contracted capital expenditure budgets across major operators, causing temporary delays in autonomous drone deployments. However, the imperative for touchless operations and reduced offshore platform manning accelerated adoption during the recovery phase. Remote inspection capabilities became essential business continuity tools, permanently embedding aerial robotics into standard operating procedures across global energy installations.
Competitive landscape, major players, and strategic dynamics within the Oil And Gas Drones Market analysis
The competitive ecosystem features a mix of aerospace primes and specialized UAS innovators. DJI Enterprise dominates commercial hardware supply, while specialized firms like Flyability SA engineer collision-tolerant drones for confined space internal inspections of refinery storage tanks. Strategic dynamics center on proprietary software ecosystems, regulatory compliance certifications, and deep integration with enterprise asset management platforms like SAP and Maximo.
Executive summary: High-level synthesis of key findings for Oil And Gas Drones Market market size
Driven by robust enterprise demand, the Oil And Gas Drones Market is projected to surge from 18.36 Billion in 2026 to an astounding 158.48 Billion by 2033. This trajectory represents a remarkable compound annual growth rate (CAGR) of 36.06%. Success in this hyper-growth environment requires strategic alignment with autonomous BVLOS capabilities and advanced multi-sensor payload integration.
Market forecast and financial projections from 2027 to 2033
Based on our econometric modeling, the market will experience exponential acceleration between 2027 and 2033, culminating in a valuation of 158.48 Billion. This expansion is underpinned by a stellar 36.06% CAGR. Midstream pipeline operators and offshore upstream developers will account for the lion's share of this capital influx as aging infrastructure necessitates continuous, high-frequency structural health monitoring.
Segmentation analysis of the Oil And Gas Drones Market
Segmentation is categorized by type, end-use, fixed wing, multi rotor, applications, single rotor, and hybrid and nano configurations.
- By Type: Single Rotor, Multi Rotor, Fixed Wing, and Hybrid And Nano.
- By Applications: Inspection, Security And Emergency Response, and Surveying And Mapping.
- By End-Use: Focuses heavily on Oil And Gas alongside Construction, Agriculture, and Mining.
Regional market analysis and geographic distribution performance
Geographic performance exhibits distinct regional characteristics shaped by local regulatory environments and asset concentrations. North America leads adoption due to vast shale plays and proactive regulatory sandboxes. The Middle East and Africa represent high-growth frontiers driven by massive state-owned upstream infrastructure investments, while Asia-Pacific expands rapidly on the back of expanding LNG terminal construction and offshore exploration activities.
In-depth regional review of key operational markets
North America anchors global demand, leveraging extensive pipeline infrastructure spanning Canada and the U.S. Gulf Coast. Regulatory evolution by Transport Canada and the FAA is progressively enabling commercial BVLOS flights. Meanwhile, the Middle East showcases high adoption of tethered and heavy-lift drones for desert-based refinery security, enduring extreme ambient temperatures that test operational endurance limits.
Company profiles and strategic positioning of leading market participants
Industry leaders utilize diverse strategic positioning to capture market share. AeroVironment Inc. and BAE Systems plc leverage defense-grade telemetry for ruggedized industrial applications. Concurrently, specialized innovators like Quantum-Systems GmbH and Microdrones GmbH deliver precision mapping and LiDAR-equipped VTOL platforms tailored for complex topographic surveys in remote upstream extraction zones.
Porter's Five Forces analysis of the Oil And Gas Drones Market
Our analysis reveals moderate-to-high rivalry driven by rapid technological iteration. Threat of new entrants is mitigated by high regulatory certification barriers and specialized sensor integration costs. Bargaining power of buyers is tempered by the specialized nature of hazardous-environment robotics. Supplier power remains concentrated among advanced thermal and LiDAR sensor manufacturers, while substitute threats from manned aviation diminish rapidly.
SWOT analysis highlighting internal and external market factors
Strengths include high data accuracy and reduced human exposure to hazardous environments. Weaknesses involve limited flight times and payload weight constraints. Opportunities lie in autonomous AI-driven anomaly detection and offshore logistics support. Threats encompass evolving cybersecurity regulations and geopolitical supply chain bottlenecks impacting critical semiconductor and carbon-fiber raw materials.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material sourcing for airframes, including carbon fiber and rare earth elements for brushless motors. Mid-stream processes involve avionics integration, proprietary AI analytics software development, and sensor calibration. Downstream delivery involves specialized service providers deploying fleets for major energy conglomerates such as Shell, ExxonMobil, and Saudi Aramco to optimize asset integrity.
Investment insights and high-potential areas for capital allocation
Investors should target early-stage software developers specializing in automated AI defect classification and BVLOS navigation algorithms. High-potential areas also include hydrogen-powered fuel cell integration for drones, which directly addresses the industry's critical limitation regarding battery flight endurance during expansive transnational pipeline corridor inspections.
Conclusion and key takeaways for executive decision-makers
The Oil And Gas Drones Market presents extraordinary financial upside, scaling to 158.48 Billion by 2033 at a 36.06% CAGR. Stakeholders must prioritize investments in autonomous software platforms, regulatory compliance, and multi-sensor payload versatility to secure sustainable competitive advantages in this rapidly maturing industrial robotics landscape.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated using a multi-tiered research methodology. This approach combines exhaustive trade registry data, primary stakeholder interviews with chief operations and safety officers across major energy firms, and secondary macroeconomic indicators from international energy agencies to ensure unmatched analytical precision and market sizing reliability.
Scope of the report, coverage parameters, and operational limitations
This report covers global market dynamics from 2026 to 2033, analyzing specific hardware configurations, application verticals, and regional performance matrices. Limitations include the exclusion of military-grade tactical UAVs operating outside commercial energy infrastructure surveillance and localized municipal drone delivery frameworks.
Recent developments, strategic partnerships, and product launches
Recent market momentum is characterized by strategic alliances between enterprise drone manufacturers and major oilfield service providers. Companies are actively deploying automated docking stations for methane emission tracking, aligning with global net-zero commitments. Recent product launches emphasize sub-250 gram nano drones equipped with dual optical-thermal payloads for safe, close-range flare stack inspections.